Macquarie Discharge Form: How to Discharge Your Home Loan
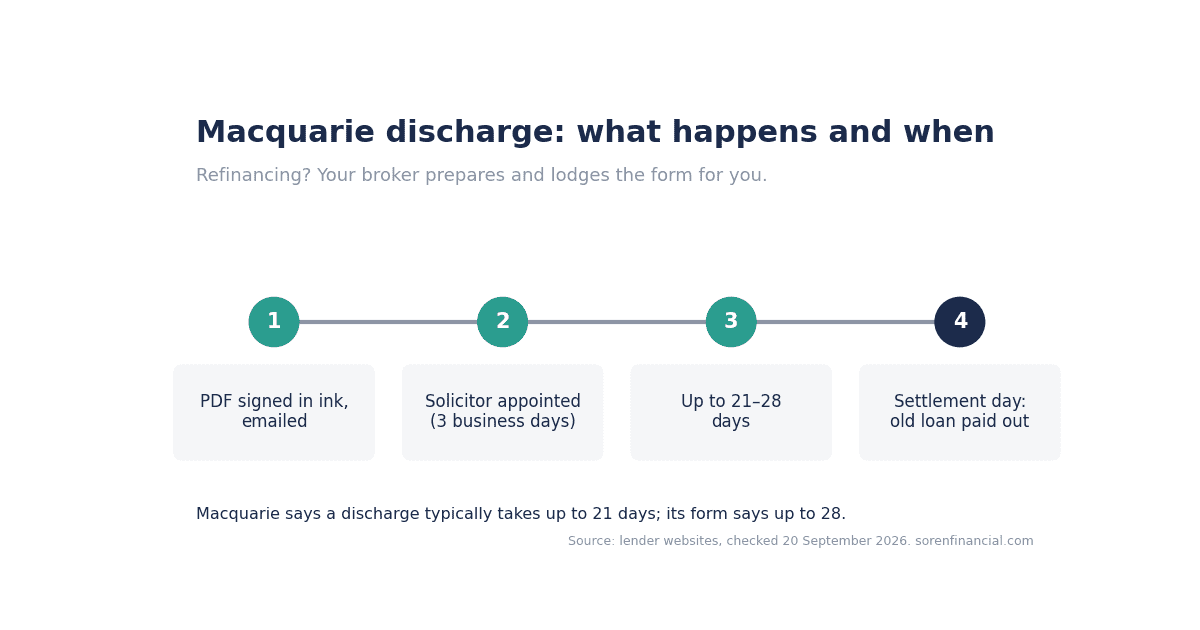
Quick answer. The Macquarie discharge form is a PDF called the Discharge Authority. You download it from Macquarie, print it, every borrower and guarantor signs it with a pen (Macquarie will not accept electronic signatures), and you email it to clientservices@mortgageinfo.com.au. Macquarie charges a $400 mortgage discharge fee, plus the NSW government’s $182.73 to register the discharge, and says a discharge typically takes up to 21 days. If a broker is refinancing you, the broker prepares and lodges this for you.
Where to get the official Macquarie discharge form
Macquarie explains the process on its discharging your home loan help page, and the form is the Macquarie Discharge Authority (PDF). Format: PDF, wet signature only. Macquarie’s own words are that all parties must sign “pen to paper” and electronically signed forms will not be accepted. If you find a fillable version on a document site, it will still need printing and signing by hand.
The signed form goes by email only: clientservices@mortgageinfo.com.au for a full discharge, or mortgagevariations@macquarie.com if you are only releasing one property from a loan with several. There is no discharge phone line; Macquarie steers questions to its app or online banking chat, and its solicitor handles the settlement side once the form is in.
What you’ll need to fill it in
- Why you are discharging: sale, loan repaid, or refinance, and if refinancing, the name of the new lender.
- Loan account number(s), borrower names and any guarantor names, and a contact number.
- Each property being released (the form has room for three).
- Full or partial discharge. For a partial, which accounts close and what the new limits are.
- Your representative: solicitor or conveyancer if selling, or the incoming lender and your broker if refinancing, with their contact details.
- A forwarding contact address for each borrower after the discharge.
- Pen signatures and dates from every borrower and every guarantor.
What it costs
| Cost | Amount | Source |
|---|---|---|
| Macquarie mortgage discharge fee | $400 (as at 20 September 2026) | Macquarie home loans product guide, August 2026 |
| Third-party settlement costs | At cost, if Macquarie’s solicitor incurs them | Macquarie home loans product guide |
| Fixed-rate break cost | Individually calculated; Macquarie says it “could be substantial” | Macquarie break costs |
| NSW government fee to register the discharge | $182.73 incl. GST (as at 20 September 2026; other states differ) | NSW LRS 2026/27 fees |
Macquarie’s $400 is higher than the $350 most of the big four charge, and the product guide adds that third-party costs, such as its solicitor’s fees or a title production charge, can be passed on at cost. The discharge fee is built into the final payout figure rather than billed separately.
On a fixed rate, the break cost is worked out on the day. Macquarie calculates the payout on a fixed loan the day before discharge and on a variable loan two days before (how Macquarie calculates the payout figure), and sends a closing statement within a week or two afterwards.
How long it takes
Macquarie’s customer page says a discharge typically takes up to 21 days to be finalised. Its broker page and the form itself say up to 28 days, so plan on four weeks. Macquarie appoints its solicitor within three business days of receiving a complete form, and after that its own staff cannot give status updates; the solicitor runs the settlement.
A quirk worth knowing: Macquarie’s solicitor holds discharge instructions for 90 days. If your refinance drags past that, the form has to be lodged again. And because signatures must be in ink, a borrower who is overseas needs a printed form couriered to them before the clock even starts.
The traps we see people fall into
Lodging before the new loan is unconditional. Macquarie’s process is slower than most and it goes to a solicitor almost immediately. Send the form before the new lender has said an unconditional yes and you have a settlement machine running with nothing to settle. Get the formal approval first.
The offset balance. At settlement Macquarie clears the loan and closes the accounts linked to it, offset included. Decide where that money goes, and before the account shuts, check the offset was actually reducing your interest. Here is how to check.
Break costs that outweigh the saving. Macquarie fixed rates have been popular, which means plenty of people are mid-term. If the break cost is bigger than a year or two of savings on the new rate, waiting for the fixed period to end can be the better move. Get the figure first.
The four-week window. The new lender is often ready in two weeks. Macquarie can take four. If nobody lines those up, you are either paying two loans or your new lender is holding funds waiting. When we refinance a client, we own that date.
Run the numbers before you send the form
A discharge only makes sense if the new loan beats the old one after the fees. Our calculators do the maths in a minute or two:
- Cost to switch calculator — the one to start with: it takes the discharge fee, the government fee and any break cost and tells you how many months until the switch has paid for itself.
- Loan repayment calculator — the new lender’s rate next to what Macquarie charges you now.
- Home loan offset calculator — what an offset account is worth to you, at either lender.
- Offset account checker — before the old loan closes, check Macquarie was crediting your offset properly. It is much harder to argue a mistake after the account is gone.
Refinancing? You don’t need to do any of this yourself
When Soren Financial refinances a client away from Macquarie, we prepare the Discharge Authority, tell you exactly where to sign, lodge it, chase the payout figure and any break cost, and book settlement so the Macquarie loan closes the day the new one opens. With Macquarie we also handle the ink-signature logistics and keep an eye on the 90-day window. The incoming lender pays us, so it costs you nothing.
Written by Mansour Soltani, Director, Soren Financial. Mansour has arranged refinances across the major banks and the non-bank lenders since 2019, and handles the discharge paperwork for every client Soren moves. Certificate IV and Diploma in Finance and Mortgage Broking Management. FBAA member. Credit Representative 527161 of Finsure Finance and Insurance Pty Ltd, Australian Credit Licence 384704.
Frequently asked questions
How much is the Macquarie discharge fee?
$400, as at 20 September 2026, plus any third-party costs at cost and the government registration fee for your state.
Can I sign the Macquarie discharge form electronically?
No. Macquarie says all parties must sign with a pen and it will not accept electronically signed forms.
How long does a Macquarie discharge take?
Macquarie’s customer page says up to 21 days; its broker page and the form say up to 28 days. Plan on four weeks from a complete, ink-signed form.
Where do I send the Macquarie discharge form?
Email it to clientservices@mortgageinfo.com.au. Partial discharges go to mortgagevariations@macquarie.com.
Does Macquarie charge break costs if I refinance a fixed loan?
Yes, if you leave during the fixed period. Macquarie calculates it individually and describes it as potentially substantial.
Is the Macquarie discharge authority the same as the discharge form?
Yes, they are the same thing. People call it a discharge authority because signing it authorises Macquarie to release the mortgage. If you are refinancing with us, we fill it in and lodge it for you.