Mortgage market update: the 3 questions our clients are asking in 2026
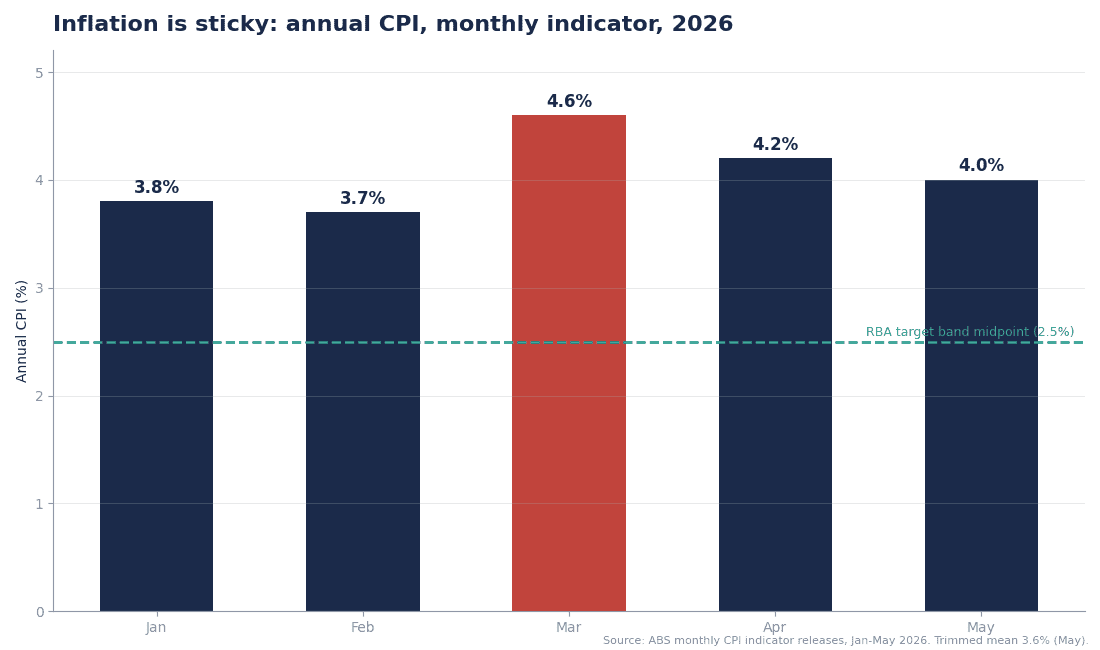
This mortgage market update writes itself, because our clients keep asking the same three questions. Fair enough too: inflation was 4.3% in the year to September, the RBA has hiked five times this year to 4.85%, and electricity prices are up 12.8% over the year now the Commonwealth rebates have ended. Here are the three questions, and the honest answers.
Got a question of your own? Send it to startnow@sorenfinancial.com — real questions from readers are where half our posts come from.
Question 1: Will rates keep going up?
Nobody knows, including the people paid to know. What we can tell you is what the market is pricing: heading into the 8 December RBA meeting, the futures pricing tracked by the OurTop10 Rate Prediction Index has it at 95.3% hold, 2.7% hike and 2% cut (as at 12 November), and all three economists who have called the meeting so far expect a hold. Read that as: after November’s rise, a pause is the strong favourite, and nobody serious is forecasting relief yet.
Question 2: Should I fix my rate?
The 2026 version of this answer is more interesting than usual, because some lenders are pricing 2-year fixed rates below their variable. Whether fixing, splitting or staying variable suits you depends on your numbers and your nerves — we wrote the full decision framework in is now the time to fix my home loan, including why a split loan is the underrated middle path.
Question 3: Can I still borrow what I could last year?
Probably not, and this is the answer people least want to hear. Each 0.25% hike trims a bit over 2% off your maximum borrowing capacity once lenders re-test your file at the higher assessment rate, so the five hikes of 2026 have taken roughly 10% or more since January. If you have a pre-approval about to expire, do not assume it renews at the same number — we covered the maths in our borrowing capacity update.
What changed since our last mortgage market update?
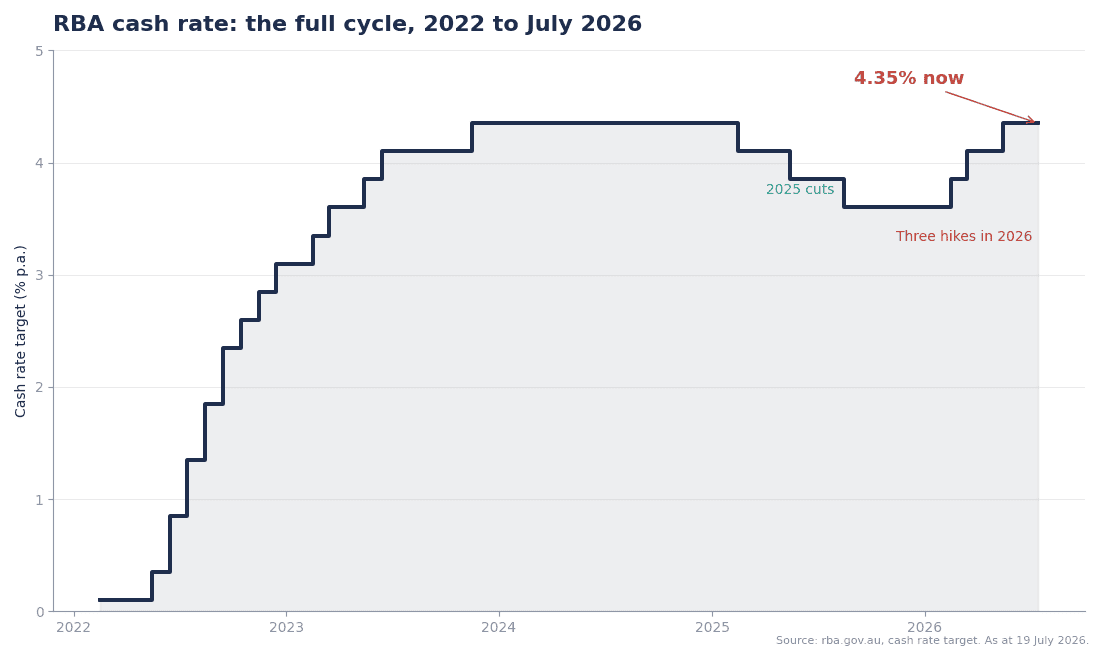
Whiplash, mostly. Through 2025 the RBA cut three times, taking the cash rate from 4.35% down to 3.60% by August, and held it there into December. Then 2026 arrived with five hikes — February, March, May, September and November — and the cash rate is now 4.85%. That’s half a percent higher than where the whole round trip started. The households who did well out of it were the ones who banked the 2025 cuts as extra repayments instead of extra spending; the ones hurting are those who borrowed to their limit at the bottom.
What this mortgage market update means for you
Three takeaways. If you are holding a loan, benchmark your rate now — repricing is free and the loyalty tax is real. If you are about to buy, get your pre-approval refreshed at today’s rates rather than relying on one issued before the September and November rises. And if you are on the fence about fixing, make the call on your numbers, not the news cycle. We publish a mortgage market update whenever the questions coming into our inbox change, so the fastest way to stay current is to send us yours.
Moral of the story: the market is asking harder questions in 2026, but they all have workable answers if you run the numbers early. Get in touch at startnow@sorenfinancial.com, or start with our calculators. Client reviews on OurTop10.
About the author
Mansour Soltani
Director, Soren Financial
Mansour leads Soren Financial, working with clients across home loans, refinancing and property investment. A regular media contributor to ABC, Domain and Australian Broker, he holds a Certificate IV and Diploma in Finance and Mortgage Broking.
View full profile →